How to move from earning money to building assets and eventually achieving financial freedom.
There is a difference between making money, growing money and building wealth.
Someone can earn ₦2 million every month and still be financially broke. Another person can earn ₦300,000 monthly but steadily build assets, savings and investments that improve their financial position over time.
The difference often comes down to how they manage their money.
You don’t necessarily become wealthy by earning more. You become wealthy by developing a system that helps you earn, save, invest and grow your money.
I recently came across an interesting post by Sharran Srivatsaa on X, where he explained what he calls the Wealth Ladder.
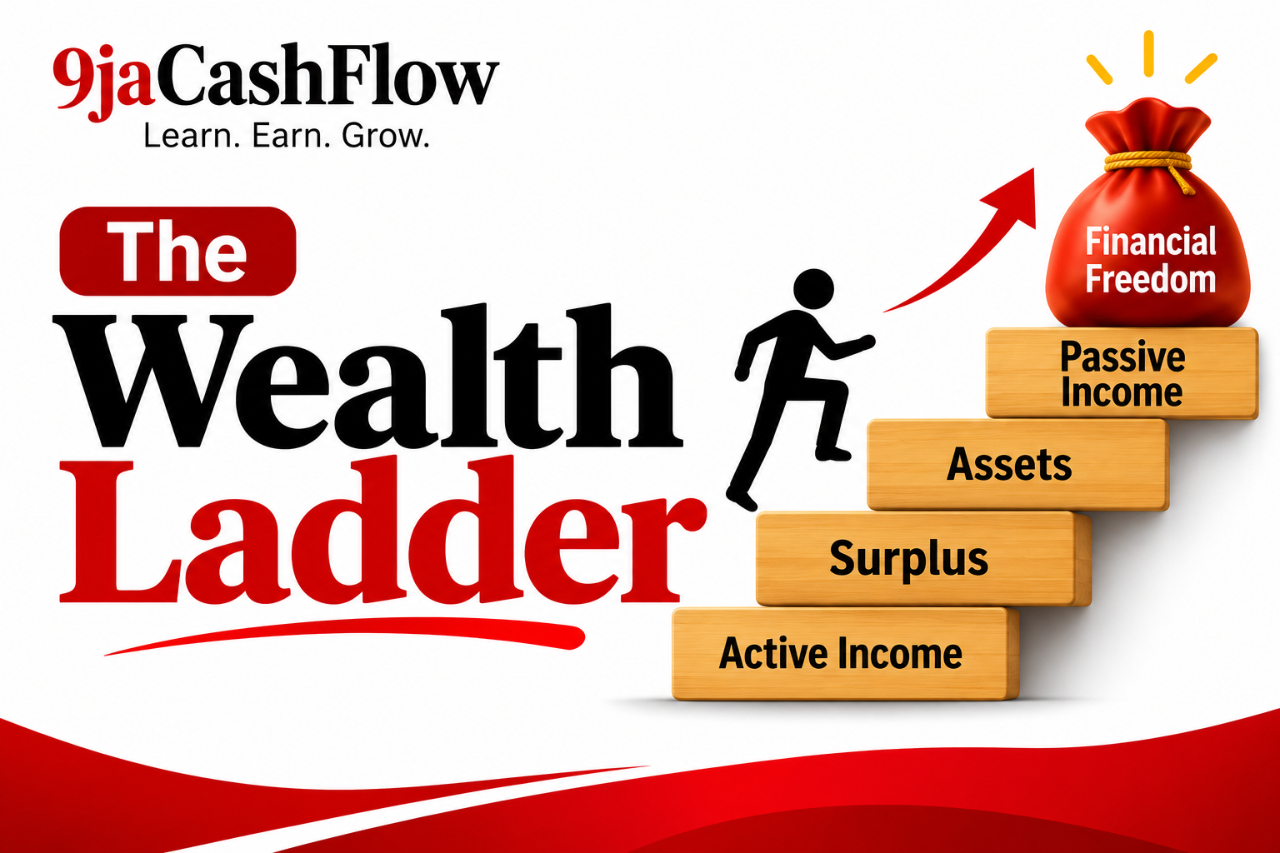
It is a four-stage framework that explains how people can move from depending entirely on active income to building income-generating assets and eventually achieving financial freedom.
I found the framework worth sharing because it simplifies some important financial principles that many people overlook.
Let’s break it down.
First, How Do You Stay Poor?
Before discussing how to build wealth, consider three habits that can keep you financially stuck:
- Not having a financial system.
- Spending more than you earn.
- Risking everything you have for the possibility of making a quick fortune.
These habits can undermine even a good income.
You need a system that helps you manage your money, control your expenses, build capital and make informed financial decisions.
This brings us to the four stages of the Wealth Ladder.
1. Active Income: Learn to Earn
The first rung of the wealth ladder is active income.
Active income is money you earn by exchanging your time, skills or services for payment.
Examples include:
- Salaries from employment.
- Income from freelancing.
- Professional fees.
- Consulting services.
- Business income that requires your direct involvement.
- Payments for skills such as programming, marketing, sales, design and accounting.
At this stage, your primary objective should be to generate enough income to cover your monthly expenses.
If you earn ₦200,000 monthly but spend ₦250,000, you are operating at a deficit.
However, if you earn ₦500,000 and spend ₦300,000, you have moved into a better financial position.
One of the fastest ways to improve your active income is to develop high-value skills that people and businesses are willing to pay for.
Don’t just look for a job or business opportunity. Ask yourself what valuable problems you can solve and how much the market is willing to pay for those solutions.
The more valuable your skills become, the more opportunities you can create to earn.
2. Surplus: Learn to Keep Some of What You Earn
The second rung is creating a surplus.
A surplus is simply the money left after paying your expenses.
The calculation is straightforward:
Active Income – Monthly Expenses = Surplus
For example:
If you earn ₦500,000 monthly and spend ₦350,000, your monthly surplus is ₦150,000.
That ₦150,000 is important because it gives you the opportunity to save, invest and build wealth.
Unfortunately, many people make the mistake of paying everyone else first and themselves last.
They receive their salaries, pay bills, buy things, entertain friends and spend on other needs. By the end of the month, nothing remains.
Instead, develop the habit of paying yourself first.
Allocate a percentage of your income towards savings and investments before spending on unnecessary things.
You don’t have to start with a huge amount. You can begin with 5%, 10% or 20%, depending on your financial circumstances.
The important thing is to develop a consistent saving habit.
Remember, you cannot build substantial wealth if you spend everything you earn.
3. Assets: Make Your Money Work for You
The third rung is acquiring assets.
An asset can be broadly defined as something you own that has economic value. However, at this stage of the wealth ladder, we are particularly interested in income-generating assets.
These are assets that can pay you for owning them.
Examples include:
- Rental properties.
- Dividend-paying stocks.
- Real estate investment trusts (REITs).
- Government and corporate bonds.
- Certain agricultural investments.
- Businesses that generate income without requiring your constant involvement.
Consider the difference between owning a car for personal transportation and owning a vehicle that generates income through a properly managed transport business.
Both vehicles have value, but only the latter is being used as an income-generating asset.
Similarly, keeping money in cash may provide liquidity, but inflation can reduce its purchasing power over time.
This is why you should gradually move beyond simply accumulating money and start acquiring productive assets.
Sharran introduces an interesting concept at this stage: TIGA (Tiny Income-Generating Asset).
The idea is to start small rather than wait until you have millions before investing.
Some examples from his post include:
1. VNQ
A US-listed fund that invests in real estate investment trusts (REITs). It provides investors with exposure to income-producing real estate through a publicly traded fund.
2. SCHD
A US-listed dividend equity ETF that invests in selected dividend-paying companies and distributes income to investors.
3. Individual Dividend Stocks
Companies such as Apple, JPMorgan Chase, Coca-Cola and Chevron have historically paid dividends to shareholders.
However, investing in individual companies carries company-specific risks. Dividend payments are also not guaranteed.
4. Index Funds with Distributions
An example is VOO, which tracks the S&P 500 Index and distributes dividends.
These are examples from the US investment market. Nigerian investors should also consider local investment opportunities, currency exposure, transaction costs, taxation, accessibility and regulatory requirements before investing.
The important lesson is not necessarily to buy these particular investments.
It is to understand the principle: Start acquiring assets that can generate income and potentially appreciate in value.
You don’t need to own an entire shopping mall before you can participate in real estate investment. You don’t need to own an entire company before you can become a shareholder.
Start with what you can afford, understand what you are buying and build gradually.
4. Passive Income: Let Your Assets Generate Income
The fourth and final rung is passive income.
Passive income is money you earn from assets, investments or systems that do not require your constant direct involvement.
There are different ways to build it.
Through money:
- Investing in dividend-paying stocks.
- Owning rental properties.
- Investing in income-generating funds.
- Holding interest-bearing investments such as bonds.
Through effort and intellectual property:
- Building an affiliate marketing business.
- Creating digital products.
- Writing books that generate royalties.
- Developing software with recurring subscriptions.
- Creating content that generates advertising revenue.
Notice something interesting?
You can use either money or effort to build future income.
For example, you can invest money in a rental property and earn rental income. Alternatively, you can spend time creating an online course that generates sales long after you have finished producing it.
The ultimate objective is to build income streams that don’t depend entirely on your daily physical presence.
According to the Wealth Ladder framework, you reach financial freedom when your passive income exceeds your monthly expenses.
For example:
If your monthly expenses are ₦500,000 and your passive income consistently generates ₦600,000, you have crossed an important financial milestone.
You are no longer entirely dependent on active work to maintain your lifestyle.
Of course, passive income is rarely completely effortless. Investments require monitoring, properties require maintenance, and digital businesses require occasional updates.
But the objective is to reduce your dependence on exchanging your time directly for money.
How Much Can You Build Over Time?
One important lesson about wealth creation is the power of compounding.
You don’t necessarily need to start with a huge amount of money. What matters is how much you can consistently invest, how long you invest and the returns you achieve.
One practical exercise is to use an investment or compound interest calculator.
Enter:
- Your current age.
- Your existing savings or investment capital.
- How much you can contribute monthly.
- Your expected annual investment return.
- How many years you intend to invest.
You can experiment with hypothetical annual returns of 7% or 10% to see how different assumptions affect your potential wealth.
However, remember that these are illustrative assumptions, not guaranteed investment returns. Actual returns vary, and inflation, taxes, fees and currency movements can affect your final purchasing power.
The purpose of this exercise is to make your financial goals measurable.
When you see what consistent contributions over 10, 15 or 20 years could potentially achieve, long-term investing becomes easier to understand.
The best time to start building wealth may have been 20 years ago. The next best time is today.
Which Stage of the Wealth Ladder Are You On?
Take a moment to assess your current financial position using these four questions:
1. Active Income: Is my monthly active income greater than my monthly expenses?
2. Surplus: Do I consistently keep a percentage of my income every month?
3. Assets: Do I own productive assets that generate income or have the potential to appreciate in value?
4. Passive Income: Can my passive income cover my monthly expenses?
Your answers will help you identify where you currently stand and what you need to work on next.
Final Thoughts: Stop Chasing Money, Start Building a System
One thing I particularly like about the Wealth Ladder is that it reminds us that wealth creation is a process.
You don’t have to jump from earning a salary directly to owning multiple properties or living entirely on passive income.
There are stages to this journey.
First, learn how to earn money.
Then, learn how to keep some of what you earn.
Next, use your surplus to acquire productive assets.
Finally, build income streams that reduce your dependence on active work.
Don’t rush the process or put your entire financial future at risk trying to skip stages.
If you are currently struggling to generate income, focus on developing valuable skills and building a business or career.
If you already earn enough to cover your expenses, work on creating a surplus.
If you have accumulated savings, start learning about productive assets and sensible investment opportunities.
And if you already own assets, think about how to grow their income-generating capacity.
Wealth is not just about how much money you make. It is also about how much you keep, what you own and how much income your assets generate.
Build your wealth ladder one rung at a time.
Learn more to earn more.
Salam.
Source and Further Reading
This article was inspired by Sharran Srivatsaa’s post on X, where he introduced his four-part Wealth Ladder framework.
Original post: https://x.com/sharran/status/2119784652269388142
Disclaimer: This article is for educational and informational purposes only. It is not financial or investment advice. Always conduct your own research and consider consulting qualified financial professionals before making investment decisions.
9jaCashFlow Insights — Practical insights. Financial wisdom. Real experiences.